How Much Revenue Does Your Business Really Need?

Project Lighthouse · Lesson 014
How much revenue does my business need? It starts with the profit your business must produce. More sales won’t necessarily give you the business—or the life—you want. Here’s how to work backward from your financial goals to the revenue your business actually needs.
How Much Revenue Does My Business Need? Start With the Destination
Ask a business owner how much revenue they want next year, and you’ll probably get an answer.
“$1.5 million.” “$2 million.” “Ten percent more than last year.”
Now ask a different question: How much revenue does your business need to generate to provide the income, financial security, and future you’re working toward?
That’s usually a harder question. Most owners build revenue targets by looking at last year’s sales and adding a percentage. But that approach starts with the business’s history rather than the owner’s destination. And those aren’t necessarily the same thing.
Start With What the Business Needs to Accomplish
In our previous lesson on business owner compensation, we examined why paying yourself shouldn’t simply mean taking whatever money happens to be available.
That includes taxes, debt obligations, reinvestment, financial reserves, and a return for the capital and risk you’ve committed to the business. These aren’t all expenses on your profit and loss statement. Many represent uses of cash after profit has been earned. But they matter when determining what your business needs to produce.
Step 1: Calculate What Profit Must Fund
Let’s return to the fictional business we’ve followed through recent lessons. The owner receives a reasonable salary, already included in operating expenses. Now consider what the business must provide beyond that salary.

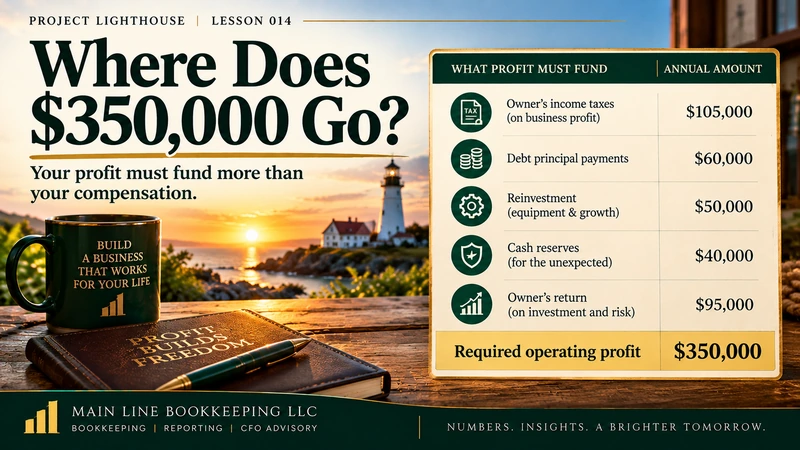
| What profit must fund | Annual amount |
|---|---|
| Owner’s estimated income taxes on pass-through business profit | $105,000 |
| Debt principal payments | $60,000 |
| Equipment and reinvestment | $50,000 |
| Building cash reserves | $40,000 |
| Owner’s return on investment and risk | $95,000 |
| Required operating profit | $350,000 |
This is a simplified planning model. Operating profit is our starting point, but actual cash available also depends on depreciation, working capital, financing, and other adjustments.
Taxes are real cash obligations. Depending on how the business is taxed, owners may owe income taxes on business profit even when the money remains in the company. The $105,000 is an illustrative planning estimate to review with a CPA.
Debt principal consumes cash without reducing operating profit. And owners deserve a return on their investment. If the business provides nothing beyond reasonable pay for the owner’s labor, the owner may have created a demanding job rather than an investment that rewards the risks of ownership.
Try this with your own business: Estimate what profit must fund beyond your compensation—taxes, principal payments, reinvestment, reserves, and your desired return. Add those amounts together.
The original financial plan projected $296,000. That’s a $54,000 gap we can actually do something about.
Step 2: Add the Cost of Operating the Business
The business expects annual operating expenses of $650,000, including the owner’s salary. To generate $350,000 in operating profit, it must produce:
That’s what must remain after direct costs to cover overhead and generate the required operating result.
Step 3: How Much Revenue Does My Business Need at 43% Margin?
The business expects a 43% gross profit margin. The calculation is straightforward:
$1,000,000 ÷ 43% = $2,325,581
Rounded, that’s $2.33 million. The original plan called for $2.2 million in sales. At the same margin and overhead level, the business needs approximately $126,000 in additional revenue to reach its revised profit target.
That’s considerably more useful than simply declaring that sales should increase by 10%.
Step 4: What If You Improve Margin Instead?
What happens if the business improves gross profit margin instead of relying entirely on additional sales?
| Gross margin | Required revenue |
|---|---|
| 40% | $2,500,000 |
| 43% | $2,325,581 |
| 45% | $2,222,222 |
| 47% | $2,127,660 |
Each revenue level produces the required $1 million in gross profit at its respective margin. The difference between 40% and 47% is more than $372,000 in required sales.
But there’s an even more interesting possibility: What if the business keeps revenue at $2.2 million and improves its margin instead?
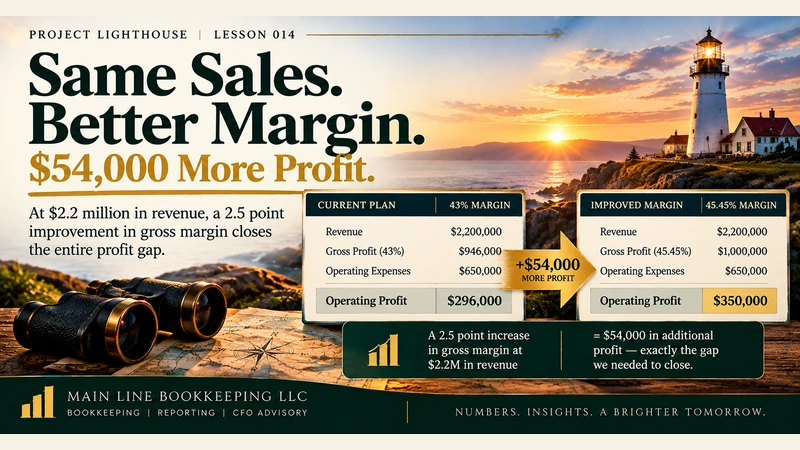
At $2.2 million in revenue, moving from 43% to approximately 45.45% gross margin generates about $54,000 in additional gross profit. That’s exactly the shortfall we identified in Step 1, assuming operating expenses remain unchanged.
Same sales. Roughly 2.5 percentage points more margin. Financial goal achieved.
That isn’t necessarily easy. But it changes the management conversation. Instead of asking only, “How do we sell more?” the owner can ask, “Where are we losing margin, and what can we do about it?”
Even one percentage point of gross margin at $2.2 million in sales represents approximately $22,000 in additional gross profit. Better pricing, purchasing, labor efficiency, job costing, and customer mix can all contribute. The point isn’t to assume unlimited margin improvement; it’s to recognize that revenue and margin are two different levers.
Step 5: Test the Target Against Reality
A mathematical revenue target isn’t automatically an achievable business plan. Before adopting it, ask:
Capacity: Can employees, equipment, and systems support the necessary sales?
Pricing: Can your prices deliver the required gross margin?
Customer mix: Are you pursuing profitable work or simply filling the schedule?
Cash flow: Can you fund payroll, materials, receivables, debt, and reinvestment while producing that revenue?
Overhead: Will greater volume require additional people, vehicles, facilities, or management?
Owner return: Will the result actually support your financial goals after cash obligations?
There’s a useful sanity check, too: $350,000 of operating profit on roughly $2.33 million in revenue represents an operating margin of approximately 15%. Compare that target with the economics of your industry and your own operating history. If it isn’t realistic, rethink pricing, costs, capacity, or the target itself.
The U.S. Small Business Administration’s guide to managing business finances offers additional guidance on financial planning and understanding your numbers.
And remember: profitability does not guarantee cash will be available when you need it. For a practical starting point, see our 13-week cash flow forecast lesson. That difference between profit and cash is also where we’ll go next week.
The Lighthouse Principle
Revenue is not the destination. It’s one of the tools that gets you there.
A business generating $3 million in sales without adequate margins, cash flow, or owner return may be less successful than one generating $2 million with stronger economics. The right revenue target isn’t necessarily the biggest number. It’s the number that supports the financial results you want, at margins your business can realistically sustain.
Three Questions Worth Asking This Week
- What must my business’s profit actually fund beyond my compensation?
- What gross margin must we achieve to produce that profit?
- What revenue level—and operating capacity—will make those numbers possible?
If you can’t answer those questions confidently, your next step probably isn’t setting a larger sales target. It’s building a better financial model.
And that’s exactly the kind of work that turns bookkeeping information into business decisions.
Main Line Bookkeeping provides bookkeeping, financial reporting, and CFO advisory services that help business owners make better decisions.
A profitable business can still run out of cash. Next week, we’ll explore the difference between earning the profit you need and having cash available when you need it.
One Comment